Sizing is not a smaller version of picking. It is the thing that decides whether a real edge survives a bad run. Two questions get confused: how much should one bet be, and how much should be on the table at once. The second gets almost no coverage, and it is the one that ends bankrolls.
Free. No account and no subscription. Needs macOS 14 or later on a Mac with Apple silicon (M1 or later). 34.9 MB, notarised by Apple.
Fractional, always
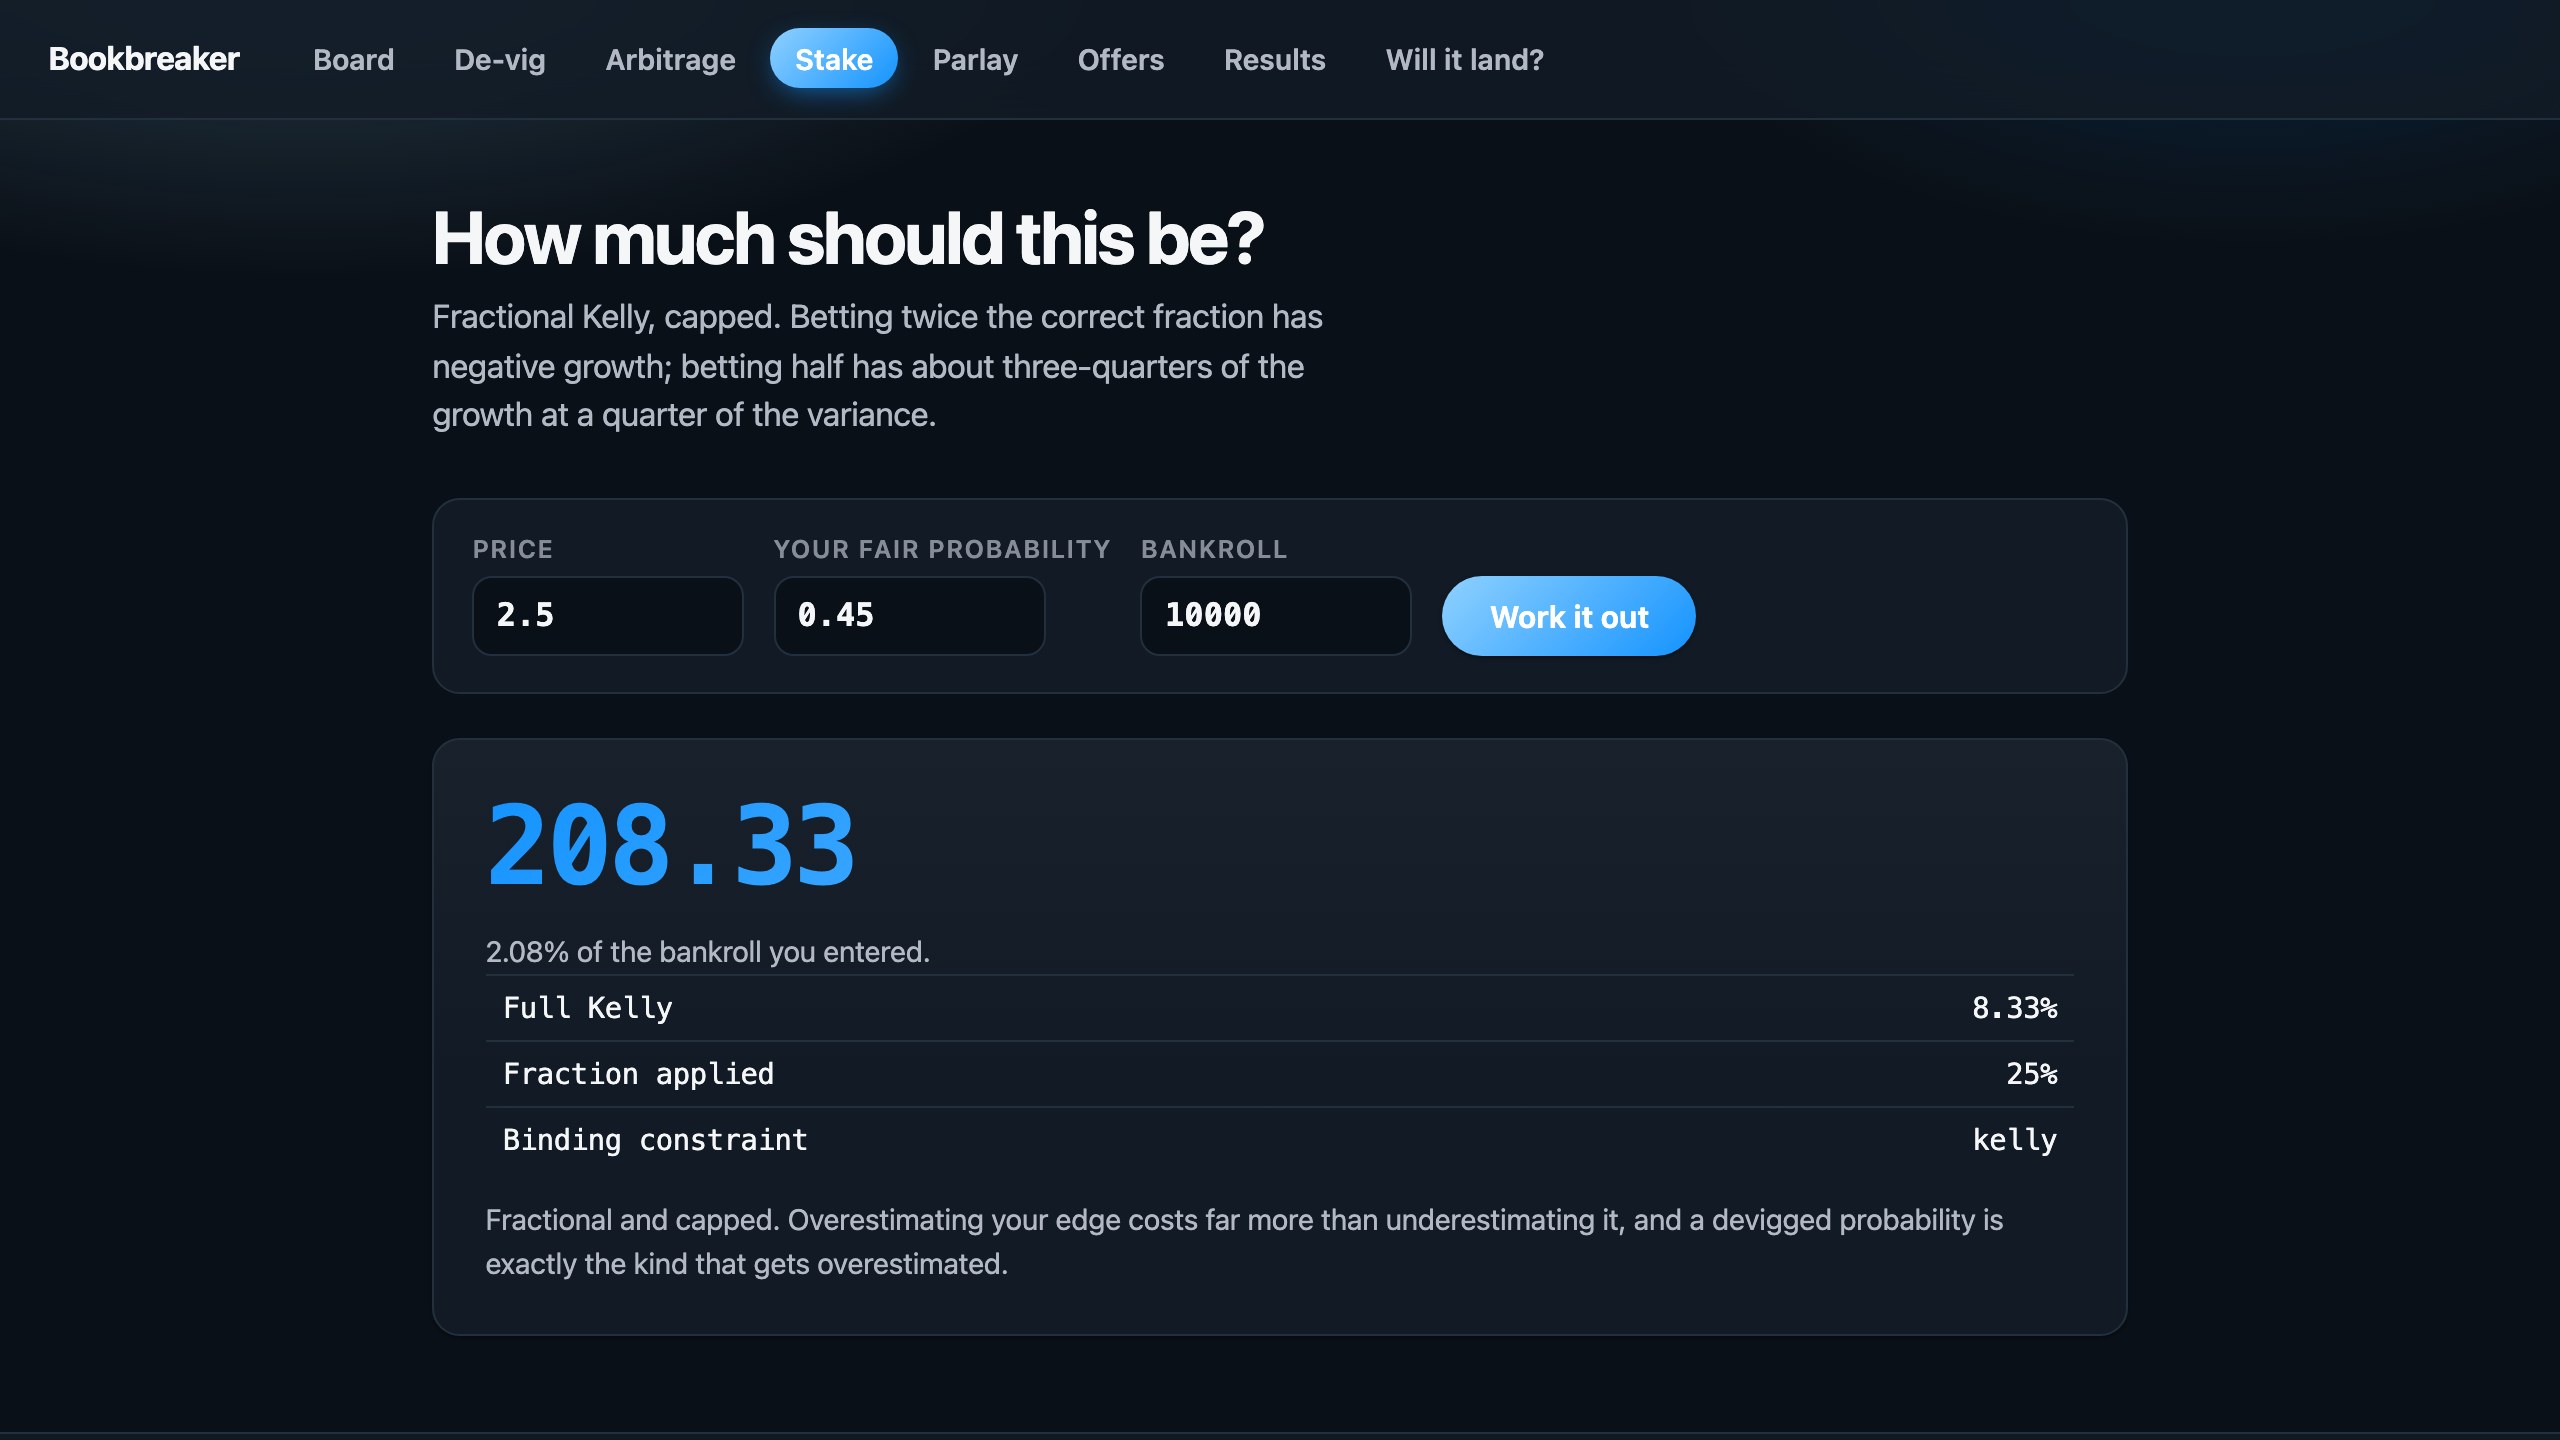
Kelly gives the growth-maximising stake given the true probability. You have an estimate with an error bar, and the penalty is asymmetric. Betting twice the correct fraction has negative growth. Betting half keeps about three-quarters of the growth at a quarter of the variance. Overestimating costs far more than underestimating, and devigged estimates are exactly the kind that get overestimated.
Cap every bet regardless
Cap one bet at 5% of bankroll whatever Kelly says. Kelly on a genuine 30% edge and on a stale line ask for the same stake, and the cap is what makes the difference between them survivable. On a 20,000 bankroll that is 1,000.00.
How much should be live at once
Above 25% of bankroll on the table at the same time, the question stops being about any single bet. That money cannot be re-deployed, re-priced or hedged if the correlation you did not measure turns out higher than you assumed.
Count correlated bets once
Twelve bets on one evening's slate are not twelve bets. They share weather,
pace, injury news and a referee. For n bets with average pairwise
correlation ρ, the number of independent bets you are really holding is
n / (1 + (n-1)ρ):
| Positions | At ρ = 0.15 | At ρ = 0.45 |
|---|---|---|
| 2 | 1.7 | 1.4 |
| 4 | 2.8 | 1.7 |
| 8 | 3.9 | 1.9 |
| 12 | 4.5 | 2.0 |
| 20 | 5.2 | 2.1 |
At 0.45, twelve positions are 2.0 independent bets, and doubling them to twenty gets you to 2.1. Past a handful of correlated bets, adding more stops buying diversification and only adds stake.
So the single-bet cap has to shrink as the book fills. Holding eleven correlated bets, the 1,000.00 that was right on an empty book becomes 409.96. For genuinely independent bets the individual optima are still right, and shrinking them would be superstition: at ρ = 0 the factor is exactly 1.0 and every bet stays full size.
Measure the correlation, do not assume it
ρ can be read from your own settled record: group bets that resolved together, and see how much their combined results swing against what independence predicts. It needs 30 settled bets and 20 multi-bet groups before it is worth anything; below that the honest answer is a labelled prior rather than a number. The effective bets calculator does the count.
Judge the sizing separately from the picking
Money return and flat-bet return answer different questions: what happened, and what would have happened staking level. The gap between them is the only direct read on whether your sizing earned anything. How to track it →